Logistics & Transportation Financing, Compared
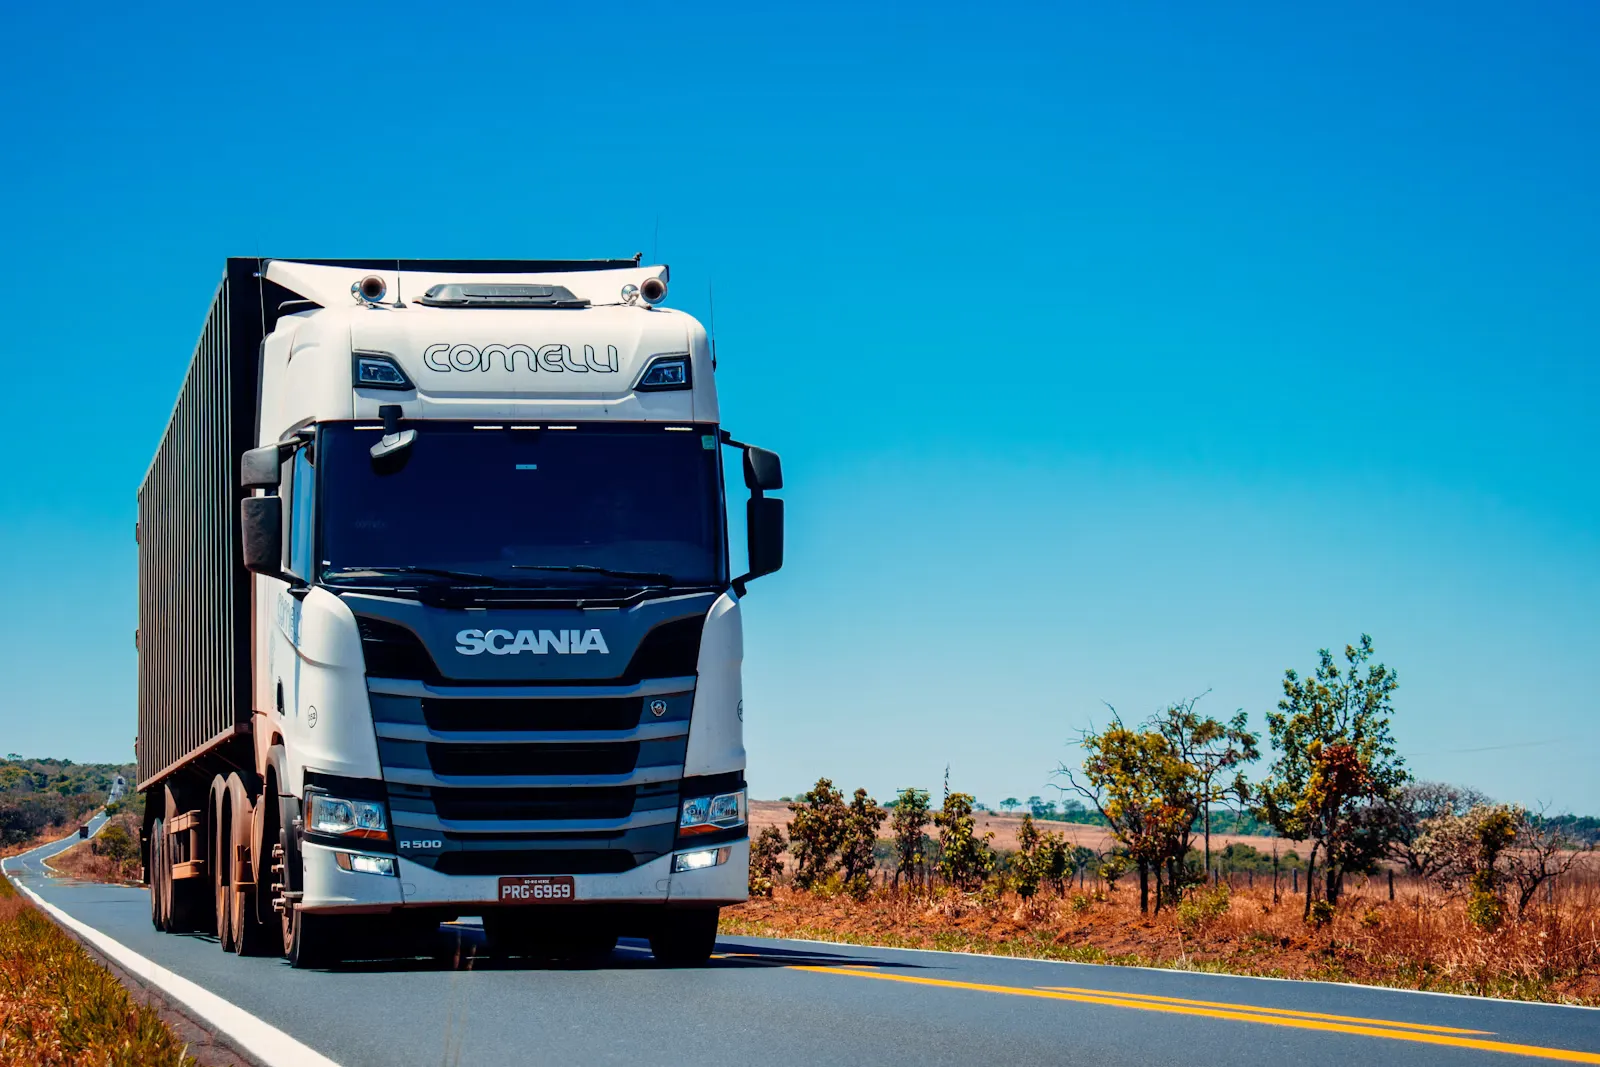
A load delivers today. The shipper's invoice often doesn't pay out for 30 to 90 days. Meanwhile fuel, driver pay, and the truck note are due every week regardless. This matrix filters 92 lenders down to the ones who actually underwrite around a freight payment cycle.
Lenders who understand a load sheet
Every entry here cleared the same bar: will it factor a freight invoice, does it understand fuel-cost volatility and shipper payment terms, and how fast can it move when a truck is sitting idle over a repair.
AI-powered underwriting with no minimum credit score requirement. Decisions issued in as little as 3 hours based entirely on monthly business revenue, with a rate-match guarantee and zero paperwork.
- Max Amount
- $10K – $5M
- Funding Speed
- Same Day
- BBB Rating
- A-
Working capital loans, MCAs, equipment financing, and SBA products available from a single lender. 4-hour approval with transparent fees and no hidden costs. In operation since 2010.
- Max Amount
- $5K – $600K
- Funding Speed
- 24 Hours
- BBB Rating
- A+
10-minute application with no hard credit pull. OnDeck reports to all three business credit bureaus, helping you build business credit as you repay. Renewal available after 6 months.
- Max Amount
- $5K – $400K
- Funding Speed
- Same Day
- BBB Rating
- A+
Over $3 billion funded to US small businesses since 2006. Offers term loans, lines of credit, revenue-based financing, equipment leasing, and SBA loans — all with no prepayment penalties.
- Max Amount
- $10K – $5M
- Funding Speed
- 24–48 Hours
- BBB Rating
- N/A

Revenue-based approval accepts credit scores from 500, focusing on business cash flow rather than personal credit history. Early payoff discounts reduce your total cost of capital.
- Max Amount
- $5K – $1.5M
- Funding Speed
- 72 Hours
- BBB Rating
- A+
Sets no minimum credit score and still turns applications around in about four hours, with funding as fast as the same day terms are accepted. All costs are disclosed upfront before signing.
- Max Amount
- $5K – $2M
- Funding Speed
- Same Day
- BBB Rating
- A+
The load moves this week. The invoice pays whenever the shipper gets to it.
Fuel, driver pay, and equipment costs are due continuously. Freight revenue, by contrast, is billed after delivery and often doesn't settle for 30 to 90 days on standard broker or shipper terms. Four points across the year expose that mismatch most.
The winter freight slowdown
Shipping volume typically dips after the holidays, and winter weather adds delays and unpaid detention time, while the truck payment and insurance premium stay exactly the same.
Spot market rates swing hard
Freight rates and fuel costs both move with capacity and demand this quarter, and a rate dip can compress margin on a lane that was profitable just weeks earlier.
Pre-peak capacity build-up
Carriers add trucks and drivers ahead of the holiday shipping surge, committing to payroll and equipment costs before that volume, or the revenue behind it, actually arrives.
Peak volume, standard payment lag
Trucks run full through the holiday season, but standard net-30 to net-90 shipper terms mean that revenue often doesn't land until well into the following quarter.
The load runs on a schedule. Getting paid for it runs on someone else's.
Trucking is one of the few industries where costs, fuel, payroll, insurance, are entirely fixed and continuous, while revenue arrives in a lump sum weeks after the work is actually done. Here's where that gap tends to bite hardest.
Per-mile margins are thin and fuel is the variable that can flip them negative
A committed lane rate doesn't move with the fuel market, so a spike in diesel prices between quoting a load and delivering it can quietly turn a profitable run into a break-even one.
Equipment down for repair keeps costing money while it earns nothing
A truck or trailer sidelined for repair still carries its note, its insurance, and its permit costs, all while generating zero freight revenue until it's back on the road.
A driver expects that week's pay whether the shipper has paid or not
Drivers are typically paid weekly regardless of whether the invoice for last week's loads has cleared, which means payroll obligations routinely outpace collected freight revenue.
Winning a dedicated contract can require adding trucks before it's signed
A large shipper or a new dedicated lane often expects proof of capacity before committing, which can mean adding equipment or drivers on spec ahead of any guaranteed freight.
A good used truck or a smaller carrier's fleet doesn't wait for savings
The chance to add trucks at a fair price, or to acquire a smaller carrier's routes and equipment, surfaces on its own timeline, independent of how much cash has been set aside.
Freight invoices sit on standard terms whether or not you can wait
Once a load delivers, the revenue is earned, but net-30 to net-90 shipper terms mean that money isn't actually spendable until the payment cycle finishes running its course.
Equipment financing and freight factoring almost never come from the same lender
A bank that finances trucks often doesn't offer invoice factoring, and a factoring company won't lend on a truck purchase. Finding that out one application at a time costs real driving time.
Applying lender by lender
Matched against the full matrix at once
Six recurring costs, six different financing fits
Fuel and payroll are constant, but they're not the only pressure points. Here's how financing typically gets allocated across a carrier or brokerage, and which product tends to fit each need.
Driver payroll and fuel
Driver pay and fuel costs run continuously regardless of when a shipper's invoice actually settles, which is the single most common reason carriers factor freight.
Fleet maintenance and parts
Routine maintenance and part inventory get ordered ahead of breakdowns, which a revolving credit line can fund without pulling from operating cash.
DOT compliance and permits
Inspection costs, permits, and compliance requirements are recurring obligations that come due whether or not that quarter's freight volume supports them easily.
Trucks and trailers
Revenue-generating equipment can serve as its own collateral, which typically clears underwriting faster than an unsecured request.
Fleet expansion or a carrier acquisition
Adding several trucks at once or acquiring a smaller carrier's routes and equipment needs a large lump sum committed up front and repaid over several years.
Consolidating short-term advances
Carriers who leaned on several quick advances to bridge a slow-pay stretch often return a year later to combine them into one lower-cost term loan.
Matched to the specific pressure point
Each card links to a ranking built specifically for logistics and transportation borrowers, not a general small-business list with the same lenders reshuffled.
Equipment Financing
Finance a truck, a trailer, or a full fleet upgrade with the equipment itself as collateral, preserving cash for fuel and payroll.
Working Capital Loans
Keep payroll and overhead current through a slow freight season or a fuel-price spike, with most carriers approved within 24 hours.
Business Line of Credit
A revolving buffer against unpredictable maintenance and fuel costs, drawn only when a gap actually shows up and repaid as freight revenue lands.
SBA & Long-Term Loans
Lower rates and longer terms for a fleet expansion, a terminal purchase, or acquiring another carrier, in exchange for a slower, document-heavy approval process.
Freight Invoice Factoring
Built specifically for trucking. Advances cash against a delivered load's invoice, often within 24 hours, instead of waiting out standard net-30 to net-90 shipper terms.
Small Business Loans
Not sure yet which category fits your operation? Compare general small business loan options across every lender and size, then narrow from there.
Term loan or line of credit: the use case decides
A term loan delivers a fixed sum for a known, one-time cost. A line of credit sits ready for whenever a fuel spike or a maintenance bill actually needs it. Most carriers end up using both, alongside freight factoring for day-to-day cash flow.
Term loan
- How it worksOne lump sum, repaid on a fixed schedule over a set term
- Best fitA defined, one-time cost like a truck purchase or a fleet expansion
- PaymentsA consistent monthly amount, easy to build into the budget
- Once it's fundedAdditional funds require a new application
- Typical range on this page$25,000 to $2,000,000, longer terms for SBA
Line of credit
- How it worksA revolving limit, drawn against and repaid, then drawn against again
- Best fitRecurring, unpredictable needs like maintenance or a fuel-price spike
- PaymentsInterest applies only to the portion actually drawn
- Once it's approvedIt stays available for the next slow stretch without reapplying
- Typical range on this page$10,000 to $500,000, renews as it's repaid
Underwriting criteria, broken down by product
Weighting differs lender to lender, but the general shape of what's required holds across most of the matrix.
Best for a fleet expansion or a carrier acquisition where total cost matters more than speed, and the business can wait two to six weeks for approval.
Best when the truck or trailer itself can secure the loan, which tends to offset a thinner credit file.
Best for payroll or a maintenance bill during a slow freight quarter, where revenue history matters more than a clean credit score.
Best for freight factoring, where the shipper's creditworthiness on a given invoice matters more than the carrier's own credit history.
Ranges reflect typical published criteria across the lenders in our matrix and can shift by lender; exact requirements are confirmed at the offer stage, not before.
Typical qualification criteria
- Time in business: Most lenders want 6 or more months of operating history; new owner-operators have fewer, factoring-weighted options.
- Monthly revenue: Commonly $15,000 to $30,000 per month, though several lenders in our matrix set no fixed floor.
- Credit score: Ranges from no minimum on factoring and revenue-based products to 650+ for the lowest advertised rates.
- Collateral: Equipment loans are secured by the truck or trailer; factoring is secured by the freight invoice itself.
Documents to have ready
A complete file up front is what separates a same-day offer from a week of back-and-forth.
Four steps, built around a carrier's pace.
Describe what the operation needs
Loan purpose, amount, and how long you've operated. The intake runs on a soft check and takes about two minutes, with no impact to your credit.
Review only what you'd realistically qualify for
The matrix filters out anything below your revenue or credit tier automatically, leaving a short, comparable list of real offers.
Check the total cost, not just the payment
Origination fees and effective APR, or factoring fees on an invoice, are shown clearly, since the payment alone rarely tells the full story.
Get funded and get the next load booked
Freight factoring and working capital lenders in our matrix can often release funds within 24 hours; SBA and larger term loans take longer.
Not a generic lender list, retrofitted for a fleet
Screened for freight-based lending
A lender who won't factor a freight invoice or finance revenue-generating equipment doesn't make this matrix, no matter how competitive their general rate looks on paper.
Full cost shown up front
Origination fees, effective APR, or a factoring rate sit next to the headline figure, since the payment alone rarely represents what the financing actually costs.
A soft check before anything else
Matching happens before any lender touches your real credit file, so comparing offers here doesn't cost you anything toward the loan you end up choosing.
Ranked on fit, not referral payout
Placement reflects how well a lender matches your file, not which one pays the biggest commission for the spot — a distinction not every comparison site in this space makes.
Criteria confirmed with lenders directly
Credit thresholds, revenue floors, and funding timelines are pulled from each lender and rechecked monthly rather than estimated from outdated marketing copy.
Built to stay current
Rates and eligibility windows in this segment shift often, so the matrix is rebuilt on a rolling basis instead of published once and left to go stale.
Every operation type carries its own capital profile
The underwriting logic holds across the board, but typical deal size and cash-flow pattern shift by operation type. Find the guide closest to your business.
Owner-Operators
Single-truck freight factoring
Small Fleet Carriers
Fleet financing, factoring
Freight Brokerages
Working capital, carrier payments
Last-Mile Delivery Services
Vehicle financing, route staffing
Moving & Storage Companies
Truck and equipment financing
Specialized & Heavy Haul Carriers
High-value equipment financing
Warehousing & 3PL Providers
Facility and equipment financing
Courier Services
Fast-cycle receivables financing
What owners actually ask before they apply
Does checking my options here affect my credit report?
No. Matching against the lender matrix runs on a soft inquiry only. A hard pull happens only once you formally accept a specific lender's offer and move into their underwriting.
How quickly can a carrier actually receive funds?
It depends on the product. Freight factoring in our matrix commonly advances within 24 hours of delivery; equipment and working capital loans typically fund a few business days after approval; SBA-backed loans can run several weeks.
Can I factor my freight invoices for immediate cash?
Yes. Freight factoring is built specifically for this: it advances cash against a delivered load's invoice, often within 24 hours, rather than waiting on standard net-30 to net-90 shipper terms.
Does fuel-price volatility count against an application?
Less than most owners assume. Lenders here generally underwrite against overall revenue and factoring volume rather than a single month's fuel margin, so normal volatility rarely disqualifies a file on its own.
Is there one universal credit-score minimum?
No. Freight factoring and several revenue-based products on this page set no fixed floor at all, underwriting primarily against the shipper's creditworthiness on a given invoice.
Can a new owner-operator or carrier qualify for financing?
The list narrows but isn't empty. Freight factoring in particular is often available to newer operators since approval leans on the paying shipper's credit rather than the carrier's own history.
How do I decide between a term loan and a line of credit?
A term loan is generally the lower-cost option for a known, one-time expense like a truck purchase. A line of credit costs more per dollar drawn but only charges interest on what's actually used, which suits a recurring, unpredictable need like a maintenance bill or a fuel-price spike.
Is collateral required for approval?
Not in every case. Equipment financing is secured by the truck or trailer, and freight factoring is secured by the invoice itself. Working capital and revenue-based products are more often unsecured, backed by a personal guarantee instead.
See your matched lenders before the next load ships.
A single soft-check submission is all it takes to see which of the 92 lenders in our matrix actually work with a freight payment cycle — no origination markup, no obligation.