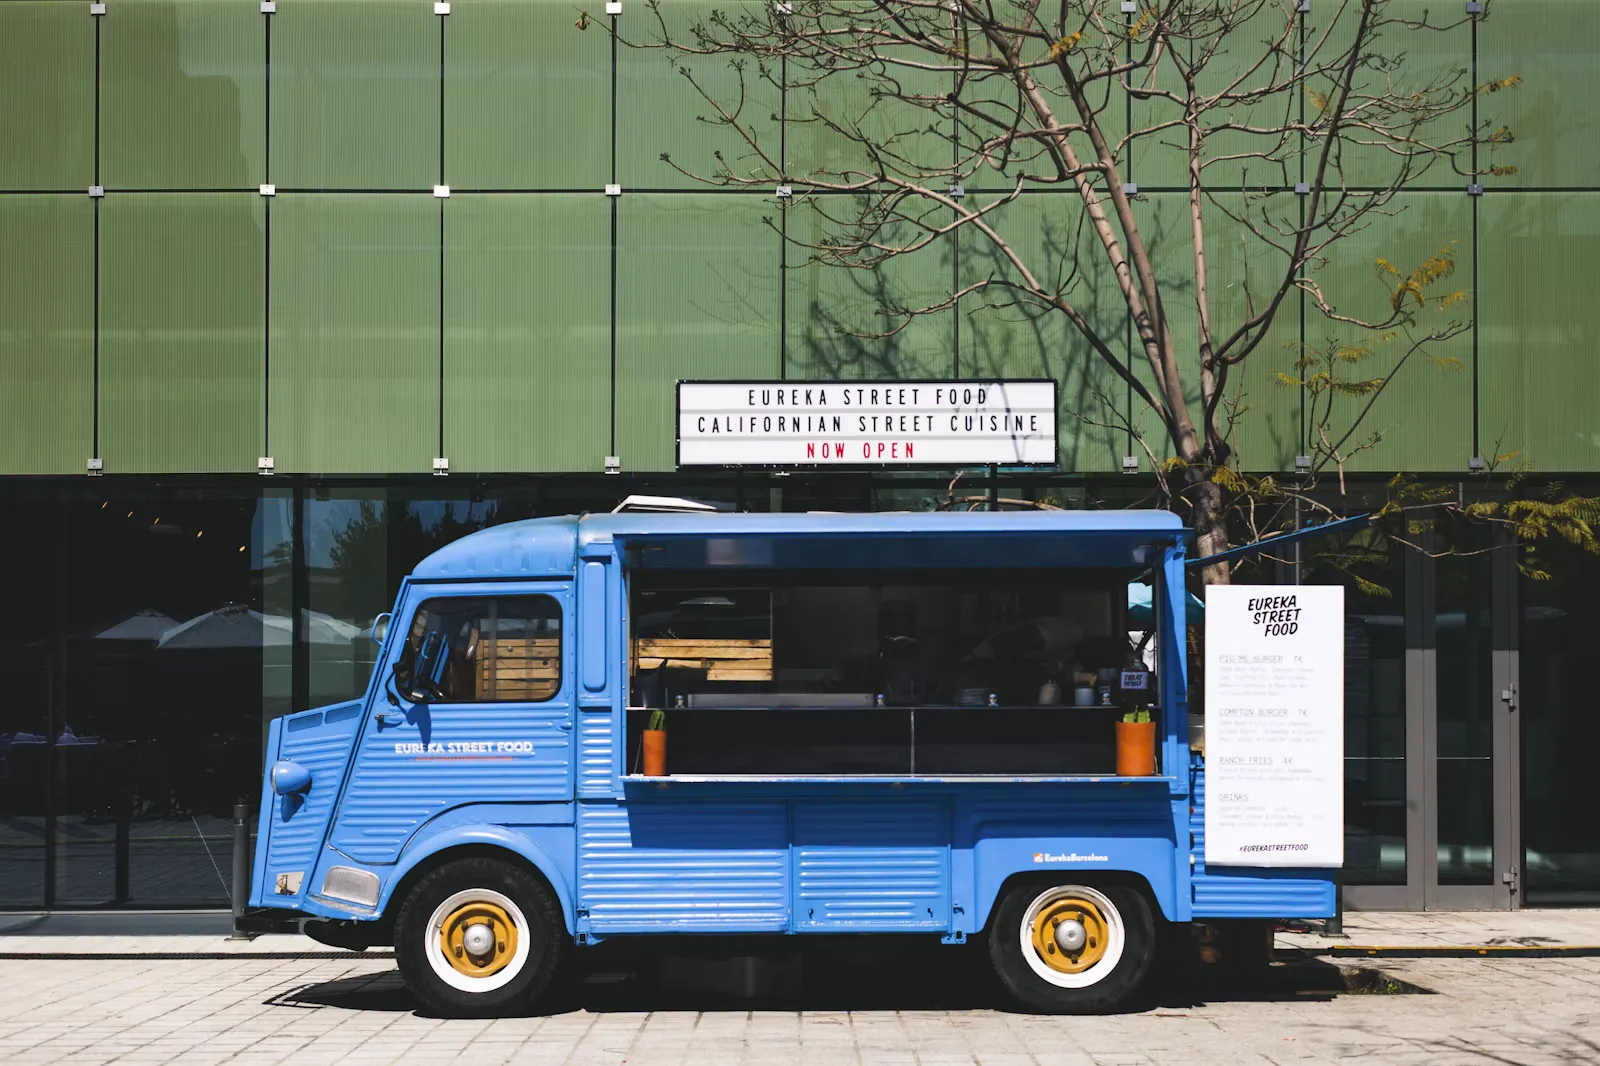
Food Truck & Mobile Food Business Financing, Compared
Your kitchen has wheels, a generator and a permit that expires. Compare lenders that fund truck purchases, build-outs, equipment repairs and slow-season cash gaps for mobile food operators.
Lenders ranked for mobile food operators
These lenders fund trucks, trailers, carts and pop-up kitchens. Compare amounts, speed and cost side by side, then request offers without a hard credit pull.
AI-powered underwriting with no minimum credit score requirement. Decisions issued in as little as 3 hours based entirely on monthly business revenue, with a rate-match guarantee and zero paperwork.
- Max Amount
- $10K – $5M
- Funding Speed
- Same Day
- BBB Rating
- A-
Working capital loans, MCAs, equipment financing, and SBA products available from a single lender. 4-hour approval with transparent fees and no hidden costs. In operation since 2010.
- Max Amount
- $5K – $600K
- Funding Speed
- 24 Hours
- BBB Rating
- A+
10-minute application with no hard credit pull. OnDeck reports to all three business credit bureaus, helping you build business credit as you repay. Renewal available after 6 months.
- Max Amount
- $5K – $400K
- Funding Speed
- Same Day
- BBB Rating
- A+
Over $3 billion funded to US small businesses since 2006. Offers term loans, lines of credit, revenue-based financing, equipment leasing, and SBA loans — all with no prepayment penalties.
- Max Amount
- $10K – $5M
- Funding Speed
- 24–48 Hours
- BBB Rating
- N/A

Revenue-based approval accepts credit scores from 500, focusing on business cash flow rather than personal credit history. Early payoff discounts reduce your total cost of capital.
- Max Amount
- $5K – $1.5M
- Funding Speed
- 72 Hours
- BBB Rating
- A+
Sets no minimum credit score and still turns applications around in about four hours, with funding as fast as the same day terms are accepted. All costs are disclosed upfront before signing.
- Max Amount
- $5K – $2M
- Funding Speed
- Same Day
- BBB Rating
- A+
Your income follows the weather and the event calendar
A truck earns only when it is parked somewhere busy and legal. The year below shows where bookings, permits and repair bills pull in opposite directions.
Cold-season lull
Fewer festivals and thinner foot traffic. The truck sits idle while insurance, commissary rent and loan payments continue.
Permits, inspections and bookings
Health permits, fire inspections and festival applications cluster before the season. Fees are paid up front, long before the first big weekend.
Peak events and equipment wear
Back-to-back weekends stress the generator, fryer and refrigeration. A failure at an event costs sales for that day and the booking fee.
Holiday catering and early winter
Corporate parties and private events add revenue, but ingredients and staff come first and invoices are often paid net 30.
Where a truck's money comes in and goes out
Mobile food income depends on location and attendance. These are the moments when expenses outrun sales, and what usually fills the gap.
Small tickets mean small cushions
Average orders are modest and food costs climb quickly. One bad week can wipe out a month of thin margin, so owners need a buffer more than a big loan.
The most expensive gear is also the most likely to fail
A truck's cooler, fryer and power supply run for hours in heat and vibration. When one fails, sales stop immediately.
You pay for the spot before you know the turnout
Festival and market fees, plus a day of prep and stock, are spent before the first sale. A rainy day can mean a loss on the booking.
Every city wants its own paperwork and fee
Health permits, commissary agreements, fire inspections and licenses vary by jurisdiction. Operating in more than one city multiplies the cost.
Growth means doubling the fixed costs
A second truck requires a vehicle, a build-out, a trained crew and a new set of permits all at once, before it earns a dollar.
Catering invoices and processor holds delay cash
Corporate catering is often invoiced, and processors may hold funds for a few days. Payroll and ingredients still have to be paid on time.
Two trucks, same breakdown, different weekends
Breakdowns happen to every truck. What changes the outcome is whether a funding source is already in place.
Scrambling after a breakdown
Funding already lined up
Six things mobile food owners borrow for
Ordered by how often each use appears among truck, trailer and cart operators comparing lenders.
The truck or trailer itself
A used step van or custom build is the largest single expense. The vehicle serves as collateral, which improves approval odds.
Kitchen build-out and equipment
Griddles, fryers, coolers, hood systems and fire suppression are required to pass inspection and to cook at volume.
Ingredient and inventory stock-up
Buying in bulk lowers per-plate cost, but cash is tied up until the stock is sold. Peak weekends require peak inventory.
Event, permit and licensing fees
Booking deposits, parking permits and health inspections are paid before sales happen.
Staff and training
Hiring a cook or window attendant for peak months means paying wages before the extra sales appear.
Marketing, POS and online ordering
Social ads, a mobile point-of-sale system and pre-order tools raise average ticket size and repeat visits.
Matched to the specific pressure point
Whether you are buying your first truck or adding a second, the right product depends on what the money is for.
Truck & Equipment Financing
Finance the vehicle, a kitchen build-out or replacement equipment, with the asset as collateral. Terms track the life of the truck or appliance.
Working Capital
A lump sum for ingredient stock-up, event fees or slow-season costs. Many lenders fund within one to two days.
Line of Credit
A revolving buffer for booking deposits, repairs and fuel. Draw when needed, repay when sales come in.
SBA & Long-Term Loans
Lower rates for established trucks with a history. Approval takes longer, but a 7(a) or microloan can fund a second truck or a commissary.
Revenue-Based Financing
Repayments flex with your daily sales through the processor, so slow weeks cost less. A fit when credit is limited.
Small Business Loans
General-purpose financing for permits in a new city, a commissary kitchen, branding or catering growth.
Term loan or line of credit: which fits a mobile kitchen?
Most food truck owners benefit from a term loan for the truck and a line of credit for the unpredictable weeks.
Term loan
- Best forTruck purchase, build-out, major equipment
- Funds arriveOnce, as a lump sum
- RepaymentFixed monthly payments
- Typical range$10K – $500K
- Watch forBalloon payments or high factor rates
Line of credit
- Best forEvent fees, repairs, inventory swings
- Funds arriveAs you draw, repeatedly
- RepaymentInterest on the drawn balance
- Typical range$5K – $150K
- Watch forDraw fees, renewal terms
Underwriting criteria, product by product
Food truck lenders usually rely on card sales and bank deposits. Select a product to see what each typically asks for.
SBA lenders prefer two or more years of operating history and clean credit. Microloans can fit newer trucks with smaller needs.
The truck or equipment secures the loan, so lenders weigh asset value and deposits. Newer owners are often accepted with a down payment.
Speed-focused approvals based on recent sales and bank deposits. Best for short-term needs, with costs higher than a term loan.
Repayment is a percentage of card sales, so it adjusts automatically in slow weeks. No fixed credit minimum at many lenders.
Ranges reflect typical published criteria across the lenders in our matrix and can shift by lender; exact requirements are confirmed at the offer stage.
Typical qualification criteria
- Typical monthly sales of $8K–$20K are common among trucks that qualify for working capital.
- Card and bank deposits that show consistent sales, ideally across multiple events or locations.
- Valid permits and licenses including health department, business license and commissary agreement.
- Vehicle information such as title, VIN, age and mileage when the truck is the collateral.
Documents to have ready
Bring these to speed up an offer, especially for a vehicle or equipment loan.
From booking to funded in four steps
Share what you need
Tell us if it is a truck, equipment, event fees or a cash buffer, and how much.
See matched lenders
We shortlist the lenders that work with mobile food operators at your sales level.
Compare offers
Look at the APR, term, fees and repayment style for each. A soft check keeps your credit unaffected.
Accept and get funded
Sign the offer you prefer. Many working capital and equipment products can fund within a day or two.
What lenders check on a mobile food business
Sales consistency
Steady deposits across slow and busy weeks look better than a few huge weekends followed by long quiet periods.
Vehicle age and condition
A newer, well-maintained truck is stronger collateral, and an older vehicle may need a larger down payment.
Permits and compliance record
A clean inspection history and active permits show a lender the business can legally operate in its markets.
Commissary and storage
A signed commissary agreement proves a compliant prep and cleaning base, which many cities require.
Time in business
Six months of trading history opens working capital; two years or more opens SBA and lower pricing.
Personal credit
For new trucks, owner credit carries more weight than business history, and a personal guarantee is common.
Mobile food businesses we serve
From a single cart to a small fleet, we match each operator to lenders that understand mobile food.
Gourmet Trucks
Chef-driven menus financing a build-out and inventory.
Food Trailers & Carts
Lower-cost operators funding a first setup.
Mobile Catering
Operators covering events and corporate lunches.
Coffee & Beverage Trucks
Espresso, smoothie and drink vendors buying machines.
Dessert & Ice Cream
Operators financing freezers and seasonal stock.
Pop-Up & Ghost Kitchens
Delivery-focused kitchens testing a concept.
Festival & Event Vendors
Seasonal vendors paying booking fees in advance.
Commissary Kitchens
Shared-kitchen owners adding equipment and capacity.
Food truck financing, answered
How much does it cost to start a food truck?
A used truck with basic equipment often starts around $50K, while a new custom build can run $100K to $200K or more, plus permits, inventory and insurance. Costs vary by city and menu.
Can I get a food truck loan with no credit history?
Yes, through revenue-based financing, equipment loans with a down payment, or microloans. Expect higher cost than a conventional term loan.
Will the truck count as collateral?
Usually yes. Truck and equipment loans use the vehicle and appliances as security, which can lower the rate and improve approval odds.
What is the difference between a factor rate and APR?
A factor rate is a flat multiplier on the amount borrowed, while APR spreads cost over time. Short terms make factor rates look cheaper than they are, so always convert to APR.
Can I finance a used food truck?
Many lenders do, often with a larger down payment for older vehicles. The age and mileage of the truck affect the term.
How fast can I get funding for a repair?
Working capital and equipment financing often fund within 24 to 72 hours once approved, and an open credit line can be drawn the same day.
Do I need a commissary to qualify?
Lenders do not require one, but most cities do. A signed commissary agreement helps show compliance and can strengthen an application.
Will comparing lenders affect my credit?
No. Comparing offers through our matrix uses a soft check, so your score is unaffected until you accept an offer.
See your matched lenders before the next event booking.
Compare food truck financing offers in minutes, with a soft check and no obligation.